
Maryland · Rowhouses, the Bay, and suburban roofs
Maryland Public Adjuster for Rowhouses, Chesapeake Wind, and Suburban Roofs
A Baltimore party wall is not an Ocean City wind file. A free policyholder review before you accept the carrier’s number.
Request a free claim review.
Tell us the Maryland address and whether this is a rowhouse leak, coastal wind, hail, or a condo loss.
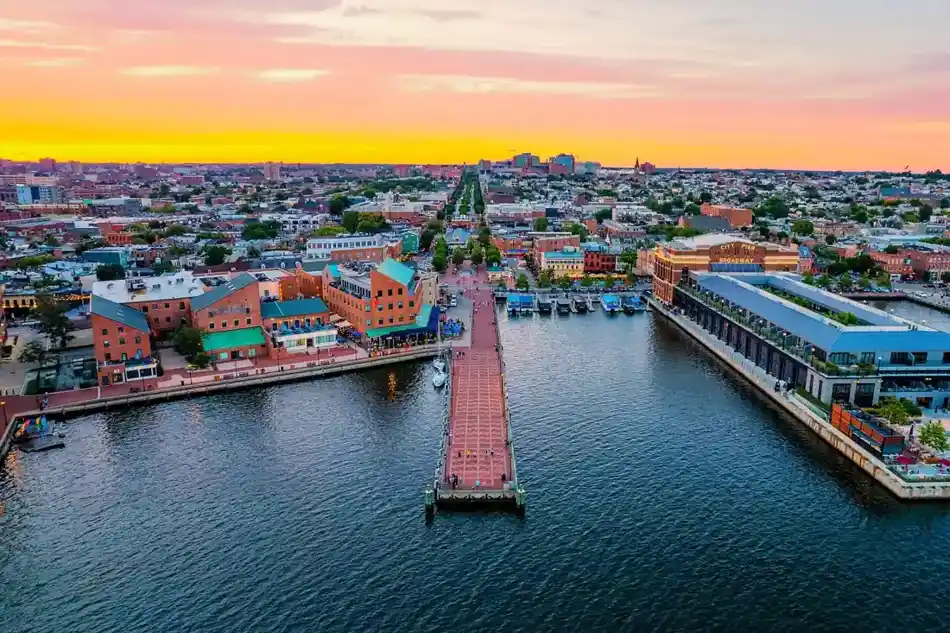
Baltimore, Maryland · Matthew Binebrink · CC BY-SA 4.0
Maryland public adjuster
Attached houses, the Bay, and the suburbs are different files.
Maryland property claims change block by block. A Baltimore rowhouse shares a roof and a wall with the neighbor. A house in Frederick does not. A condominium in Bethesda adds an association. American Financial Claims represents the policyholder, not the carrier. Call (239) 444-8101 for a free claim review before you accept an offer or give a recorded statement. You still report the loss on your policy’s timeline. The review does not replace that notice and does not create a fee.
Baltimore’s attached buildings.
Baltimore, Towson, and Dundalk are where party walls, flat roofs, and shared downspouts decide the claim. Water from the house next door, a failed rear addition, or a roof that spans two owners does not price like a detached colonial. The estimate has to say whose building, whose policy, and how far the water traveled. Fire in a rowhouse moves through cocklofts. Smoke in the house that did not burn can still be a contents and cleaning question, and only if the form allows it. We read that language instead of assuming. See water damage, fire and smoke, and roof damage.
North and west of the city, Bethesda, Rockville, Silver Spring, Gaithersburg, and Germantown mix high-value houses with condominiums. The master policy may own the roof and the exterior while your floors, cabinets, and betterments sit on the unit form. A loss assessment is its own paragraph. Bring both policies. Columbia, Laurel, Bowie, and Waldorf are suburban wind and water files: tree strikes, architectural shingles, and interior wetting after an opening. If the check repaints and does not rebuild the slope, look at underpaid claims.
The Bay, the ocean, and the west.
Annapolis deals with Chesapeake wind and buildings close to the water. Ocean City is a different shore: condominium towers, rental weeks, and wind off the Atlantic. Wind-driven rain through a failed window wall is not the same claim as tidal flooding. Flood is often excluded from the homeowners or HO-6 form and written, if at all, on a separate policy. We keep those photos apart. Rental calendars matter only when the form actually covers lost rents. We will not invent that coverage.
Frederick and Hagerstown sit toward the mountains, where hail and straight-line wind show up more than harbor surge. Soft metal and granule loss date a storm. Older downtown buildings still do not estimate like a Germantown production house. Commercial property and interrupted business are a separate scope under commercial claims and wind. We do not promise a settlement amount or a date.
The Maryland number, and no invented firm license.
The individual number published for Maryland on our licensing page is 3004205279. American Financial Claims does not list a Maryland firm license. We confirm status and whether we can accept the engagement before representation. This page is not a live check with the Maryland Insurance Administration. Florida firm license G288962 is the Florida firm credential we publish. It is not a Maryland firm license. City pages are service areas, not offices. The firm’s published address is in Miami.
What to send first
Declarations page, photos of the shared wall or the roof edge, the date the water or wind arrived, any mitigation invoice, and the carrier estimate or denial. If an association sent a letter, include it. Any fee is in a written contract before you sign. The review is free. We do not publish a client-authorized Maryland recovery on results. Those cases are other states and are not a forecast for a rowhouse or a bayfront roof. For legal deadlines, speak with a Maryland-licensed attorney. Your policy’s notice clause still governs when you must report.
Service areas
City pages across Maryland.
Each link is a local public-adjuster page. These are service areas, not a claim of a separate office in every city.
Maryland FAQ
Questions people ask before hiring.
General information, not legal advice. A free review does not create a fee.
Is a Baltimore rowhouse claim the same as an Ocean City condo claim?
No. Rowhouses turn on shared roofs, party walls, and whose policy owns the finish. Ocean City wind and rental condos turn on the HO-6, the master policy, and whether water came through an opening or from the tide. Call (239) 444-8101 with the address. The review is free.
My neighbor’s roof leaked into my house. Is that my claim?
It can be, depending on the policies and the path of the water. Bring your declarations page and photos of where the water entered. We will not guess which carrier owes what until we read them.
Does a homeowners policy pay for Chesapeake flooding?
Often flood is excluded or written separately from wind. Wind-driven rain through an opening is a different fact. Photos of the waterline matter. We do not assume coverage.
What Maryland license number is published?
Individual number 3004205279. We do not publish a Maryland firm license. Florida firm license G288962 is a Florida credential. We confirm status before representation.
Are the city pages local offices?
No. They are service areas.