
Oregon · Rain, smoke, and mountain roofs
Oregon Public Adjuster for Rain, Wildfire Smoke, and Roof Claims
The west side leaks differently than the high desert. A free policyholder review before you take the carrier’s figure.
Request a free claim review.
Tell us whether the Oregon loss is wind-driven rain, smoke, a freeze, or something else.
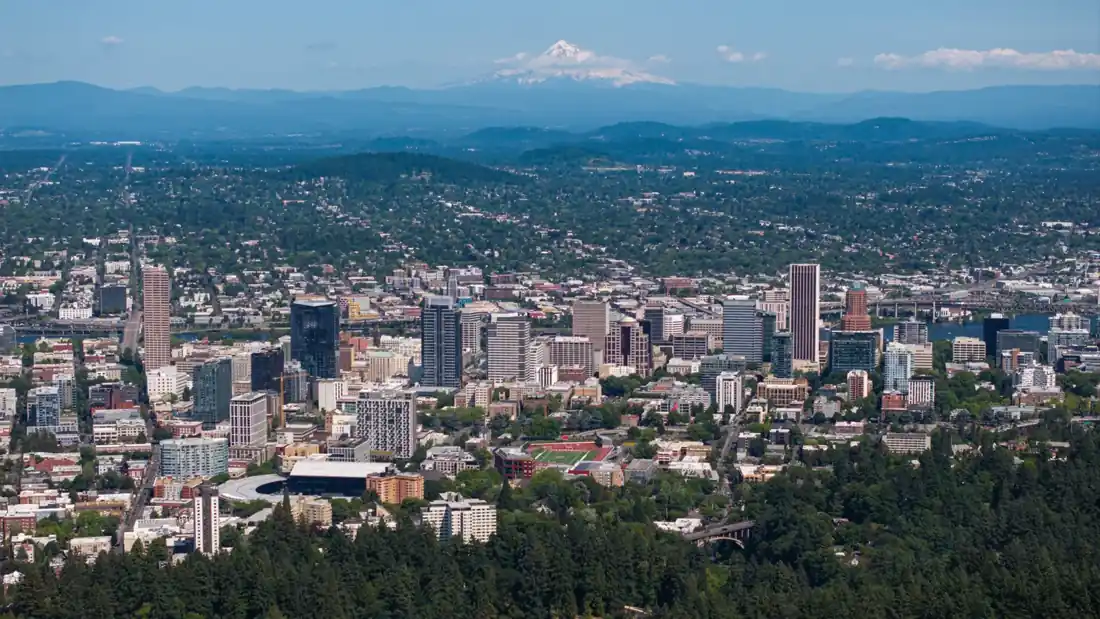
Portland, Oregon · Spicypepper999 · CC0
Oregon public adjuster
West-side rain is not a southern Oregon fire.
Oregon property claims follow the Cascades more than a state average. Weeks of wind-driven rain in the Willamette Valley and a smoke event in the Rogue Valley are both “property,” and they are documented differently. American Financial Claims is on the policyholder’s side of the file, not the carrier’s. Call (239) 444-8101 and ask for a free claim review before you accept an offer or agree to a recorded statement. You still report the loss when your policy requires it. Talking with us does not replace notice, and the review itself is not a charge.
Portland rain, moss, and older houses.
Portland, Beaverton, Hillsboro, Gresham, Tigard, Lake Oswego, and Oregon City live with atmospheric rivers. Water comes through failed flashing, skylights, and roofs that have held moss for years. Carriers like to call that maintenance. Maintenance can be true. So can an opening the storm made. The photos have to show the path: the exterior defect, the wetting below, and the dry-out, not only a stain on paint. Craftsman bungalows, cedar, and older multi-family buildings do not estimate like a new subdivision. Plumbing stacks in condominiums add a second cause that has nothing to do with the river of rain outside. See water damage, roof damage, and plumbing damage.
Down the valley, Salem, Keizer, Albany, Corvallis, Eugene, and Springfield see the same long rains, plus rental housing where the unit policy and the building policy disagree about who owns the floor. If a check already paid for paint and not the wet assembly, that is an underpaid claim question.
Bend snow, and smoke south of the passes.
Bend is not Portland with a different ZIP code. High-desert winters mean snow load, ice, and plumbing in houses that sit empty between trips. A burst line found on Friday can have been running since Tuesday. Document the drying and the source. Metal roofs and vacation finishes do not price like a close-in bungalow.
South of the range, Medford, Grants Pass, and Klamath Falls are where wildfire and smoke show up in the claim file. Flame, soot in an air handler, and smoke odor on contents are not the same coverage question. Some policies treat smoke differently from fire, and some deductibles change with wildfire. We will not tell you a fire is covered until the form says so. Photographs, inventories, and the carrier’s cause letter are the start. People ask about earthquake after a jolt. In Oregon that coverage is typically optional. We look for the endorsement and its deductible rather than treating every home form as if it included one. Commercial buildings and interrupted sales are separate from the house claim — commercial claims and fire and smoke explain how those files are built. We do not promise a result.
What the Oregon listing actually is.
American Financial Claims publishes individual numbers in 15 states. For Oregon, the number on our licensing page is 20497788. We do not list an Oregon firm license. Authorization to accept a file is confirmed before representation, and the page is not a live check with the Division of Financial Regulation. Florida firm license G288962 is a Florida firm credential, not an Oregon one. The cities below are service areas. They are not offices from Astoria to Klamath Falls. Our published office address is in Miami.
Bring this to the review
Declarations page, the week the leak or smoke started, photos of the roof and the rooms, mitigation invoices, and any denial or estimate. If the house is a rental, say whether you own the building or the unit. Any fee is written down before you sign. The first look is free. We do not publish a client-authorized Oregon recovery on results. Those cases are other states and are not a forecast for a mossy roof or a smoke claim. For legal time limits, talk with an Oregon-licensed attorney. The policy’s own notice clause still tells you when to report.
Service areas
City pages across Oregon.
Each link is a local public-adjuster page. These are service areas, not a claim of a separate office in every city.
Oregon FAQ
Questions people ask before hiring.
General information, not legal advice. A free review does not create a fee.
Is a Portland roof leak from weeks of rain covered the same way as a burst pipe?
Not necessarily. Long rain through flashing is a different cause from a failed supply line, and older cedar or plaster does not price like new drywall. Call (239) 444-8101 with the city and the source you know so far. The review is free and does not replace notice to the carrier.
Will you treat wildfire smoke as fire?
Only if the policy does. Smoke, flame, contents, and a wildfire deductible can be written apart. Bring the declarations page and the carrier letter. We will not assume the answer.
Do you handle Bend snow claims and valley water claims?
Yes, as property claims, and the photos are different. Snow load and a frozen vacant house are not an atmospheric-river file. Tell us which one it is.
What Oregon number is on your licensing page?
20497788, as an individual number. We do not publish an Oregon firm license. Florida firm license G288962 is Florida only. We confirm status before we accept a file.
Are these city links local storefronts?
No. They are service areas across Oregon.