
Rhode Island · Coast, triple-deckers, and historic houses
Rhode Island Public Adjuster for Coastal Wind, Flood, and Older Housing
Newport is not a Providence triple-decker. A free policyholder review before you accept the carrier’s number.
Request a free claim review.
Tell us the Rhode Island town and whether this is wind, flood, a triple-decker leak, or fire.
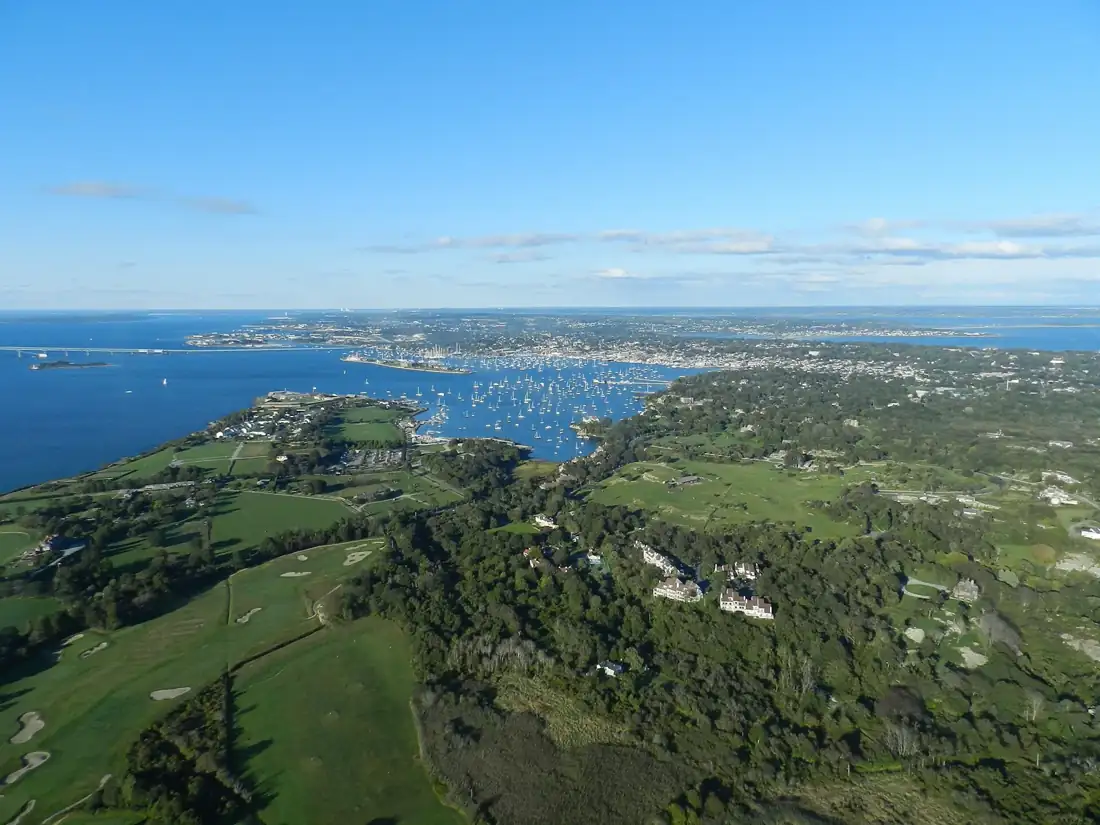
Newport, Rhode Island · MVASCO · CC BY-SA 3.0
Rhode Island public adjuster
A small state with more than one building.
Rhode Island is short on miles and long on claim types. A historic house on the water, a Providence triple-decker, and a barrier-beach cottage can all be insured, and they should not share one estimate. American Financial Claims is retained by owners and associations here, not by the company that wrote the check. Use (239) 444-8101 before you accept an offer or give a recorded statement, and ask for a free claim review. You still notify the carrier on the schedule in the policy. The review is not that notice, and it is not a fee.
Providence housing, then the bay.
Providence, Pawtucket, Cranston, East Providence, North Providence, and Woonsocket are full of older multifamily buildings. A leak in a top-floor bath can cross three units. The building policy, a unit policy, and a tenant’s interest do not automatically pay the same finishes. We read who owns the roof, the stack, and the floor before anyone treats the file as one number. Cumberland tracks that older-housing pattern more than the open beach. Fire and smoke in these buildings move through balloon frames and shared stairs. Document the path, not only the room where it started. See water, plumbing, and fire and smoke.
Warwick sits between the city and the bay: houses, some coastal wind, and ordinary roof leaks after a nor’easter. Wind-driven rain through an opening is not the same as tidal flooding. Many homeowners policies exclude flood. If both happened, the photos have to separate the roof edge from the waterline. We will not blend them to make a simpler story.
Newport, South County, and the shore.
Newport is a high-value and historic file: slate, wood, ornate interiors, and buildings that a unit-price estimate will understate. Storm wind and salt air both age a roof. The claim still needs a date of loss, not a speech about the ocean. South Kingstown and Westerly face the open shore and barrier beaches. Flood zones, wind, and erosion show up in the same week and still belong on different forms. A cottage rented in summer may also raise vacancy or rental language in the off season. Say how the house is used. Commercial waterfront property is a separate scope — commercial claims and wind damage. If the carrier already paid a number that will not restore the building, start with underpaid claims. We do not promise the figure will change.
Westerly and South Kingstown cottages that rent in summer raise another paperwork issue the Providence triple-decker usually does not: which months the house was occupied, and whether rental income is even on the form. We ask before we put lost weeks into a presentation. Off-season vacancy wording is a policy sentence, not a guess.
License language, kept tight.
Our licensing page publishes individual number 3004206535 for Rhode Island. American Financial Claims does not publish a Rhode Island firm license. We confirm status and availability before accepting representation. The page is not a live check with the Department of Business Regulation. Florida firm license G288962 is a Florida firm credential, not a Rhode Island one. Every city link below is a service area, not a local office. The firm’s published address is in Miami.
What to gather
Declarations page, photos of the roof and of any waterline, the storm or leak date, contractor or dry-out invoices, and the carrier estimate or denial. If a triple-decker is involved, note which floor and whose policy you hold. Any fee is written before you sign. The first review is free. We do not publish a client-authorized Rhode Island settlement on results. Cases there are other states and are not a quote for a Newport roof or a Providence stack. For legal deadlines, speak with a Rhode Island-licensed attorney. Your form can require faster notice than a rule of thumb.
Service areas
City pages across Rhode Island.
Each link is a local public-adjuster page. These are service areas, not a claim of a separate office in every city.
Rhode Island FAQ
Questions people ask before hiring.
General information, not legal advice. A free review does not create a fee.
Is a Providence triple-decker leak the same as Newport storm damage?
No. Multifamily stacks turn on which policy owns the pipe and the finishes. Newport wind and historic materials turn on the roof, the opening, and replacement of finishes a unit price will miss. Call (239) 444-8101 with the town. The review is free.
Does homeowners insurance pay for beach flooding?
Often it does not. Flood may be excluded or written on a separate form. Wind through a roof opening is a different question. Bring photos of the waterline and the declarations page. We will not assume coverage.
Several units got wet. Whose claim is it?
It depends on the policies. The building form, a unit owner form, and a tenant’s interest can divide the same water. Send whatever declarations you have before anyone closes the file.
What Rhode Island number do you publish?
Individual number 3004206535. We do not publish a Rhode Island firm license. Florida firm license G288962 is Florida only. We confirm status before representation.
Do you have an office in each city listed?
No. These are service areas.