$175,000
Jessica & Bryan · Bradenton, FL
View result ↗︎
Colorado · Hail, freeze, and mountain property
Front Range hail and high-country water losses. A free policyholder review before you accept the carrier’s number.
Tell us the Colorado town and whether this is hail, a freeze, or something else.
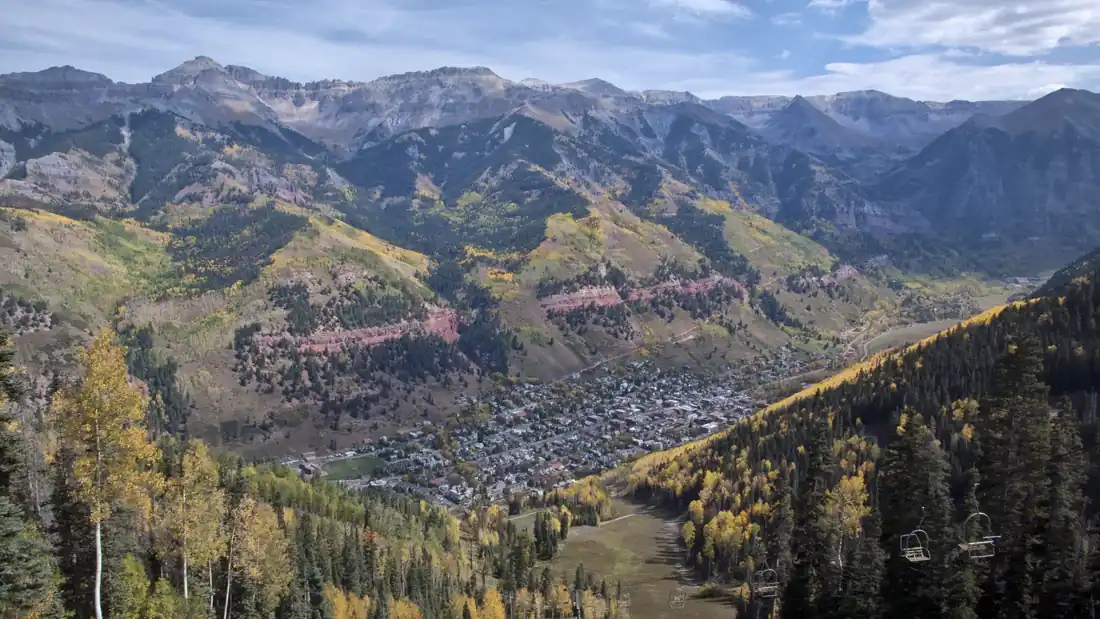
Telluride, Colorado · John Fowler · CC BY 2.0
Colorado public adjuster
Colorado property claims split by elevation as much as by storm. A July hail core over the Front Range and a January pipe burst in a ski town are both “property,” and they are not the same file. American Financial Claims is a public adjusting firm on the policyholder’s side, not the carrier’s. Call (239) 444-8101 for a free claim review before you accept a settlement figure or give a recorded statement. You still need to report the loss when your policy says to. The phone call does not replace that notice, and it does not start a fee.
Denver, Aurora, Lakewood, Arvada, Westminster, Thornton, Centennial, and Highlands Ranch sit in a hail corridor. So do Colorado Springs, Fort Collins, Boulder, Longmont, and Greeley. Impact marks soft metal first. Shingle bruises and granule loss are easy to miss from the sidewalk, and carriers often age the roof instead of dating the storm. We look for a storm date that matches the collateral — gutters, box vents, condenser fins — and then read whether the policy pays replacement cost, actual cash value, or a cosmetic limitation. Matching discontinued shingles is a frequent fight on hail and roof claims. If the check already arrived and it does not rebuild the slope, that is an underpaid claim question, not a reason to throw the letter away.
Condominium and townhome claims along the Front Range add an association layer. The master policy may own the roof while your walls, floors, and betterments sit on an HO-6. Loss-assessment language matters when the association’s deductible is large. Bring both policies if you have them. We do not guess which form pays until we read them.
Above the Front Range the losses change. Vail, Breckenridge, Aspen, Steamboat Springs, Telluride, and Estes Park see ice dams, snow load, and plumbing that freezes when a house sits empty between rentals. A burst line can soak several floors before anyone opens the door. Document the drying, not only the broken pipe — see water damage and plumbing damage. Roof decks, metal roofs, and log or timber details do not estimate like a production subdivision in Aurora. If wildfire smoke or evacuation is part of the story, coverage depends on the forms. Some policies treat smoke differently from flame, and some wildfire deductibles are their own number. We will not tell you a fire is covered until the policy says so. Photos of soot, inventories, and the carrier’s cause-of-loss letter are what make that conversation real.
Grand Junction and the Western Slope are neither a Denver hail core nor a resort freeze. Wind, older roofs, and water still show up. Pueblo sits between plains hail and southern Colorado wind. Use the city page that matches the address so the examples fit the building.
American Financial Claims publishes individual public-adjuster credentials in 15 states. The Colorado individual license number we publish is 940240. We do not list a Colorado firm-license number on this page. Firm authorization is confirmed before we accept a file, and a website number is not a live check with the Colorado Division of Insurance. Florida firm license G288962 is our published Florida firm credential. It is not a Colorado firm license. These city pages are service areas. They do not mean we operate a storefront in every town from Windsor to Telluride. See the licensing page for the directory.
Have the declarations page, storm or leak date as you know it, photos of roofs and interiors, any mitigation invoice, and the carrier estimate or denial. Short-term rental calendars help when lost rents are part of the ask, but only if the policy actually covers that exposure. If a contract makes sense, you see the fee in writing before you sign. There is no charge to look. Those are not predictions. Read published recoveries under results, then call (239) 444-8101 if your own estimate still does not match the building.
Authorized Colorado results
$175,000
Jessica & Bryan · Bradenton, FL
View result ↗︎$85,000
Arturo · Miami, FL
View result ↗︎$345,000
Church · Tampa, FL
View result ↗︎Recoveries clients authorized us to share. Every insurance claim is different, and prior results do not guarantee a similar outcome. Read the case before comparing it to your loss. All published recoveries.
Service areas
Each link is a local public-adjuster page. These are service areas, not a claim of a separate office in every city.
Colorado FAQ
General information, not legal advice. A free review does not create a fee.
Yes, if you want a second read. Call (239) 444-8101 for a free claim review before you accept an offer or give a recorded statement. Still report the loss on your policy’s timeline. The review does not create a fee and does not replace notice.
Yes, as property claims, and they are documented differently. Hail files turn on impact, roof system, and policy valuation. Freeze and plumbing files turn on the source of water, drying, and what the form covers. Tell us the town and the cause so the review starts in the right place.
No. Smoke, flame, and evacuation expenses depend on the policy. Some forms treat smoke differently from fire, and wildfire deductibles can be separate. Bring the declarations page and the carrier’s letter. We will not assume coverage.
Sometimes. The master policy and your unit policy can divide the building. Interior finishes, betterments, and loss assessments may sit on your form even when the association owns the roof. We read both documents before anyone decides the file is closed.
Individual license 940240. We do not publish a Colorado firm license number here. We confirm status and whether we can accept the engagement before representation. City pages are service areas, not local offices. Florida firm license G288962 is a Florida credential.