Commercial claims
Commercial property and business interruption claims: the basics every owner should know
For business owners and commercial property managers. When a building is damaged, the property claim and the lost-income claim tell one story. Here is how to keep both organized.
By Armando Ferrer, Licensed Public Adjuster
American Financial Claims · Florida firm license G288962
Published · Updated 6 min read
In this article (6 sections)
This article is for business owners and commercial property managers, not homeowners. If you are a homeowner, our guide to what to do after property damage is a better starting point.
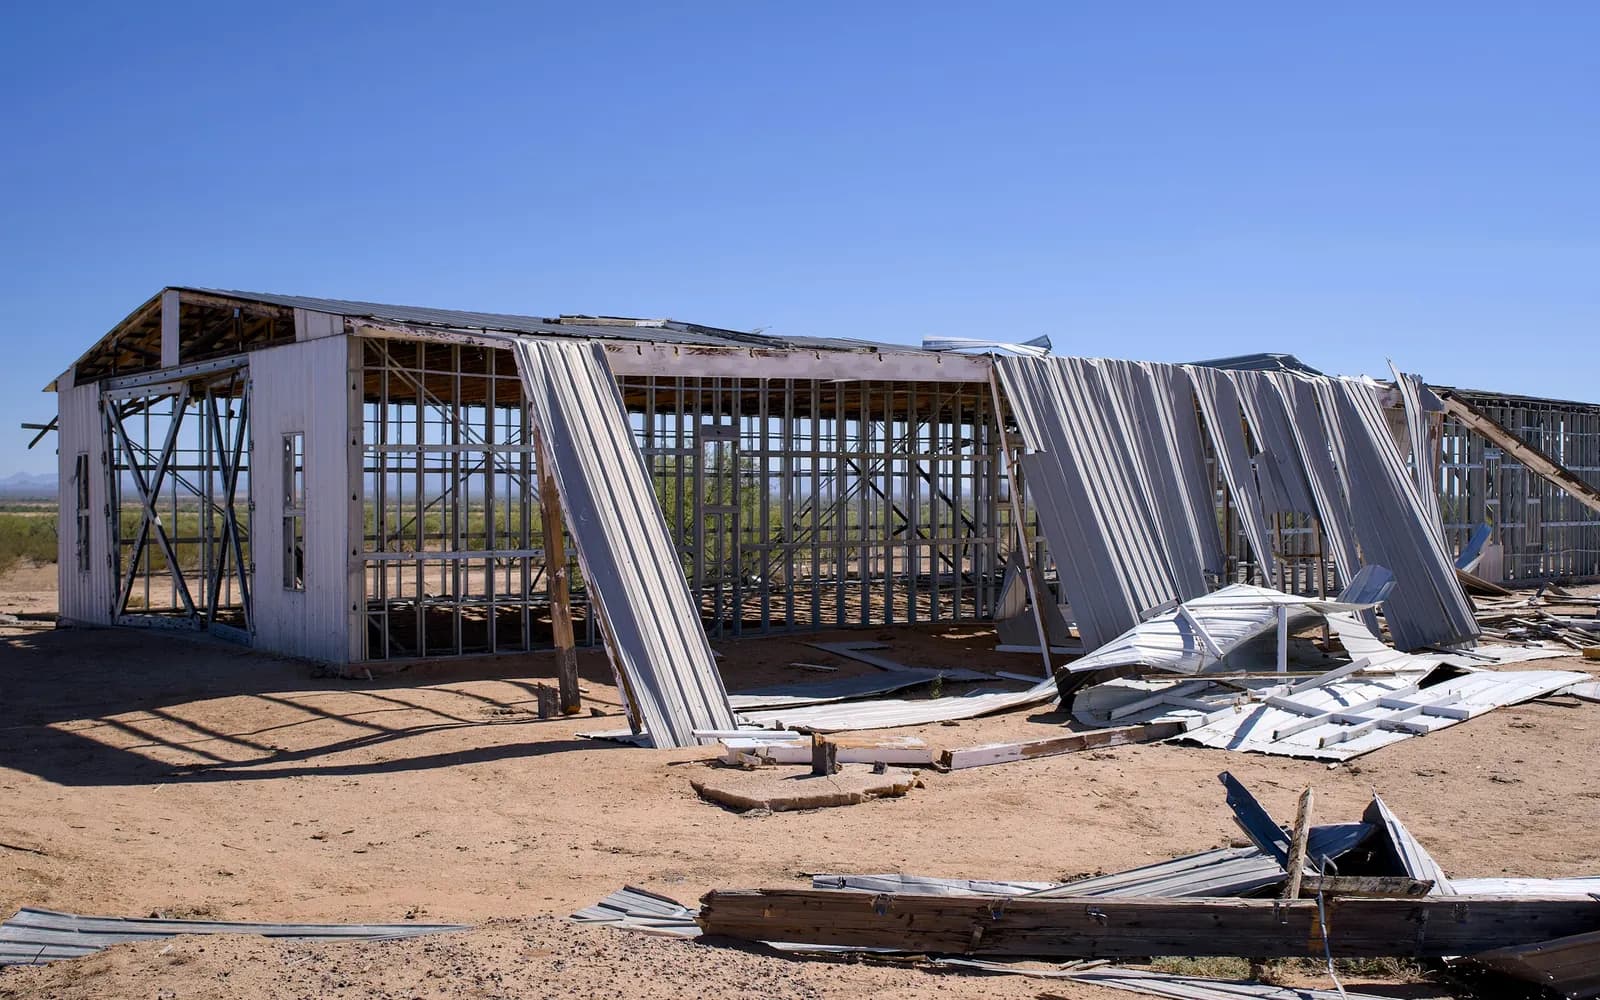
When a commercial building is damaged, two losses usually happen at once. There is the physical damage to the building, equipment and inventory. And there is the financial damage: sales that did not happen, payroll that still had to be paid and extra costs to keep operating. Many policies cover both, under different parts of the policy with different rules.
Owners often treat these as separate problems and handle the financial side last. That can make both harder. This guide explains the basics in plain language. It is educational, not legal or accounting advice, and every commercial policy is different.
One event, two connected claims
A commercial property policy may include several coverages. The names and details vary, but these are common.
- Building coverage for the structure itself
- Business personal property for equipment, furniture, fixtures and inventory
- Business income (business interruption) for lost net income and continuing expenses while operations are limited
- Extra expense for reasonable costs to reduce the interruption, such as temporary space or expedited repairs
- Civil authority or other extensions, in some policies, when access is restricted
The physical damage drives the business income claim. The longer repairs take, the longer the interruption. That is why the two need to be documented together, with the same dates.
Check your declarations
Business income coverage is not automatic. Confirm it is on your declarations page, and note any waiting period, time limit or dollar limit.
The records that make a business income claim work
Business income claims are built on numbers. The goal is to show what the business would reasonably have earned without the loss, what it actually earned, and what it spent to keep going.
Financial records to gather
- Profit and loss statements for prior periods, often by month
- Sales records or point-of-sale reports before and after the loss
- Payroll records, including employees kept on during the closure
- Tax returns for recent years
- Invoices for extra expenses: temporary space, equipment rental, overtime, expedited shipping
- Records of seasonal patterns, such as holiday or tourist-season peaks
Our guide to preparing a commercial claim document packet explains how to keep property records and business records connected without mixing them together.
The period of restoration: why the timeline matters
Many business income provisions pay for a defined period, often called the period of restoration, which generally runs from the damage until the property should reasonably be repaired, subject to the policy’s terms. Delays in repair, permitting or supply can affect how long that period lasts and how it is measured.
- Record the date operations were first limited, and how.
- Track every repair milestone: inspection, estimate, permits, contractor start and completion.
- Note delays and their causes, such as backordered materials or permit waits.
- Record the date operations partly resumed and the date they fully resumed.
- Keep the financial records for the same dates side by side with the repair timeline.
Common pitfalls for commercial claims
- Waiting to start the business income claim until the building claim is resolved
- Mixing records, so building repairs, inventory and lost income blur together
- Not tracking extra expenses that reduced the interruption
- Overlooking seasonality, which can make a slow month look like normal
- Ignoring policy conditions, such as notice requirements, proof of loss and cooperation duties
“Business interruption documentation is about clarity, not creativity. Organize what actually happened so the policy can be read against real numbers.”
Deadlines apply to commercial claims too. Policy conditions and state laws set time limits for notice, proof of loss and disputes. In Florida, section 627.70132 of the Florida Statutes sets a one-year notice deadline for new or reopened property insurance claims from the date of loss. Check your policy and your state’s rules.
Notes for landlords and associations
Owners of rental buildings and community associations face a slightly different version of the same problem. Instead of lost sales, the financial loss is often rent that cannot be collected while units are uninhabitable, or shared costs that fall on every owner while common areas are repaired.
Some commercial policies include rental value or loss of rents coverage. Where it applies, the records that matter are leases, rent rolls, notices to tenants, the dates each unit became unusable and the dates each unit was returned to service. For associations, board minutes, reserve records and correspondence with unit owners help show how the loss unfolded.
Extra records for rental and association properties
- Current leases and a rent roll as of the date of loss
- Written notices to tenants or unit owners about the damage and repairs
- A unit-by-unit list of when each space was out of service and returned
- Association board minutes and contracts for emergency work
- The master policy and any unit-owner coverage information you have
Keep in mind that building damage inside individual units may be split between the association’s master policy and each owner’s own policy, depending on the governing documents and the policies involved. Sorting that out early prevents gaps and duplicate work.
Who should be on your side
Commercial claims often involve several professionals: your accountant for the financial records, contractors and engineers for the building, and sometimes an attorney for legal questions. A licensed public adjuster can coordinate the property and business income documentation and present the claim to the insurer on your behalf.
The best time to bring a public adjuster in is right after the loss, before recorded statements, the insurer’s inspection or document requests, and before temporary repairs cover the damage. Early involvement helps avoid the most common commercial mistakes: an incomplete first estimate, a business income claim started too late, and records that do not match the repair timeline. The consultation is free.
American Financial Claims handles commercial property and business interruption claims for businesses, landlords and associations. Learn more on our commercial claims page.
Frequently asked questions
What does business interruption insurance cover?
It depends on the policy. Business income coverage generally addresses lost net income and certain continuing expenses while operations are limited by covered physical damage, subject to the policy’s terms, waiting periods and limits. Extra expense coverage may pay reasonable costs to reduce the interruption.
Do I need physical damage for a business interruption claim?
Many business income provisions require direct physical loss or damage to covered property, but some policies include extensions such as civil authority coverage. Read your policy’s business income section carefully.
What records do I need for a business income claim?
Typically prior profit and loss statements, sales and payroll records, tax returns and invoices for extra expenses, along with a timeline of when operations were limited and when repairs were completed.
Can a public adjuster help with a commercial claim?
Yes. A public adjuster can document the building and contents loss, coordinate the business income documentation with your accountant, and present the claim on your behalf.
Free claim review
Want a second set of eyes on your claim?
Send us the letter, the estimate or just a description of what happened. A licensed public adjuster will review it at no cost and tell you plainly what we see, including when we don’t see a path. No recovery, no fee.
Prefer to read first? Get the free digital edition of Armando’s book, The Insurance Game: And How To Win It. Schedule a free consult Public adjuster services Read chapter guides.
Armando Ferrer
Licensed Public Adjuster · American Financial Claims · Florida firm license G288962
Armando leads public adjusting work at American Financial Claims, a public adjusting firm based in Brickell, Miami. Armando Ferrer is individually licensed in 15 states; the firm entity license is Florida only (G288962). He is the author of The Insurance Game: And How To Win It. Consultations in English and Spanish. More about Armando.
Educational information only, not legal advice. Scenarios in this article are general illustrations, not real cases or clients. Coverage, deadlines and outcomes depend on your policy, your state and your facts, and no result is guaranteed. Statute references are to the Florida Statutes as published by the Florida Legislature; other states’ rules differ. American Financial Claims is a public adjusting firm, not a law firm.