Getting started
Property damage? Your first moves matter more than you think
The first week after a loss sets the tone for the whole claim. Here is a calm, practical order of operations for protecting your home, your family and your paper trail.
By Armando Ferrer, Licensed Public Adjuster
American Financial Claims · Florida firm license G288962
Published 7 min read
In this article (7 sections)
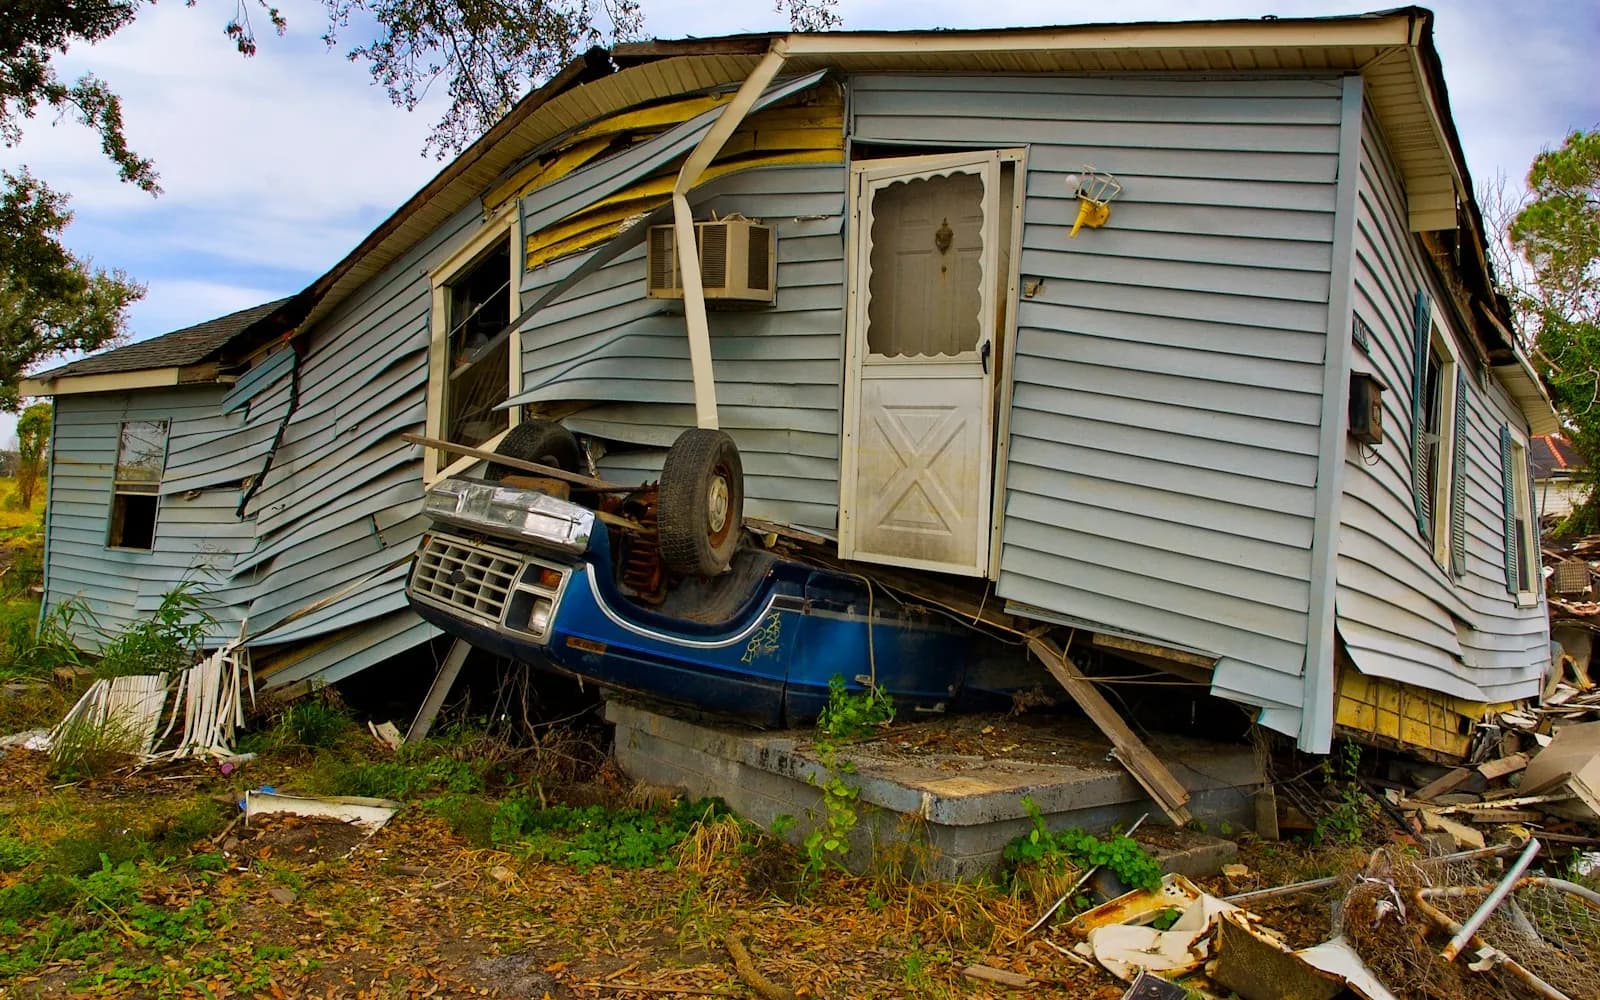
Property damage rarely arrives at a convenient time. A pipe bursts while you are at work. Smoke fills the kitchen on a holiday. A storm rips off part of the roof overnight. In the moment, most people are not thinking about insurance. They are thinking about their family, their pets and where they will sleep.
That is exactly right. But once everyone is safe, a few steady decisions in the first days can make the claim much easier later. People tend to make one of two mistakes: they rush into repairs and cleanup before anything is documented, or they freeze and wait so long that damage spreads.
This guide offers a simple order of operations. It is general education, not legal advice, and your policy and state rules always control.
Step 1: Call a licensed public adjuster first (free consultation)
If anyone is in danger, call 911 or the utility company first. Once people are safe, make your next call to a licensed public adjuster, before the recorded statement, the insurer’s inspection, signing anything or throwing damaged materials away. The first days of a claim are when the most expensive mistakes happen, and they are hard to undo later.
Calling us first does not mean delaying your claim. Your policy requires prompt notice, and we help you report it correctly and on time, protect the property and start the right record from day one. The consultation is free, and you decide what happens next.
What a first call covers
What to say when you report the claim, what to photograph before cleanup, which emergency repairs to make and which receipts to keep, and what to expect from the insurer’s adjuster.
Step 2: Make it safe
Before anything else, deal with immediate hazards. If there is fire, gas, structural damage or live electrical risk, leave and call emergency services or the utility. Do not re-enter until it is safe.
- Shut off the water main if a pipe or fixture is leaking and you can reach it safely
- Turn off power to wet areas at the breaker if you can do so without standing in water
- Keep children and pets away from damaged rooms
- Wear gloves and a mask around soot, debris or suspected mold
The simple rule
People first, then property, then paperwork. But do not skip the paperwork once people are safe.
Step 3: Prevent further damage, and document it
Most property policies expect you to take reasonable steps to protect the property from further damage. That can mean tarping a roof, boarding a window, extracting water or running fans and dehumidifiers.
The key is to document before and after. Photograph the damage, make the emergency repair, then photograph the repair. Keep every receipt and invoice. If you hire a mitigation company, ask for their moisture readings and drying logs.
Step 4: Photograph everything, in order
Good claim photos are not artistic. They are systematic. Work from the outside in, and from wide to close.
- Take a wide shot of each side of the building and each affected room.
- Take medium shots showing where the damage sits in the room.
- Take close-ups of the damage itself, with something for scale.
- Photograph damaged contents before moving or discarding them.
- Record a slow walkthrough video, narrating the date and what you see.
Our damage photo checklist covers this in more detail, including what not to risk.
Step 5: Report the claim promptly and start a claim diary
Report the loss as your policy requires and as soon as you reasonably can, ideally after a quick call with your public adjuster so you describe the damage accurately and completely. Write down the claim number, the date you reported, and the name of the person you spoke with.
Then start a simple claim diary, in a notebook or a notes app. Every call, email, visit and letter gets a line: date, who, what was said, what happens next. It feels tedious. Months later, it is often the most valuable document in the file.
Mind the deadlines
Policies and state laws set time limits for reporting claims. In Florida, for example, section 627.70132 of the Florida Statutes bars a new property claim unless notice is given within one year after the date of loss. Other states and policies have their own limits, so check your policy’s conditions section.
“A steady first week beats a perfect first week.”
Step 6: Find your policy and read the key pages
You do not need to become a policy expert overnight, but it helps to know where a few things live. If you cannot find your policy, ask your agent or insurer for a complete copy, including endorsements.
Pages worth finding
- The declarations page: coverages, limits and deductibles
- The duties after loss section: what the policy expects you to do
- Loss settlement: replacement cost versus actual cash value
- Additional living expense coverage, if you cannot stay at home
- Endorsements that add or limit coverage, such as water or mold limits
Our guide to understanding your policy explains these sections in plain language.
If you cannot stay at home
If the damage makes part or all of the home unlivable, check whether your policy includes additional living expense or loss of use coverage. Keep receipts for hotels, short-term rentals, meals above your normal grocery spending and extra mileage, and write down the date you moved out and the date you moved back. Ask your insurer what documentation it expects before you commit to a long-term rental.
Step 7: Avoid the early mistakes that shrink claims
Mistakes a public adjuster helps you avoid
- Giving a recorded statement before you understand the damage or your coverage
- Accepting a low first estimate as the final word
- Missing damage the first inspection did not look at, such as attics, cabinets or adjoining rooms
- Signing a release or cashing a check marked “final” without reading what it settles
- Missing a notice or supplemental-claim deadline
Once the property is stable and the claim is reported, the insurer will usually inspect and write an estimate. Compare it carefully with what your contractor says the repair requires. Our article on reviewing an insurance estimate walks through that.
The sooner a licensed public adjuster is involved, the fewer of these mistakes you have to fix later. We work for the policyholder, not the insurance company. Learn more about how we handle new claims, or see our pages on water damage, fire and smoke damage and hurricane damage.
For a book-connected checklist of the first 48 hours, read Property claim mistakes people make in the first 48 hours from The Insurance Game chapter guides.
Frequently asked questions
Who should I call first after property damage?
If anyone is in danger, call 911 or the utility first. Then call a licensed public adjuster for a free consultation before the recorded statement, the insurer’s inspection or signing anything. We help you report the claim to your insurer promptly and correctly, as your policy requires, and tell you which emergency repairs to make and which receipts to keep.
Can I throw away damaged items?
Photograph damaged items before disposal and keep a list. For large or expensive items, ask your insurer whether they want to inspect them first. Keeping small samples of damaged materials, such as flooring, can also help.
How soon should I report a property insurance claim?
As soon as you reasonably can, and within any deadline in your policy and state law. In Florida, a new property claim must be reported within one year after the date of loss under section 627.70132.
When should I talk to a public adjuster?
Early is often better, especially for large or complex losses, but you can reach out at any stage. A free claim review can help you decide whether representation makes sense for your claim.
Free claim review
Want a second set of eyes on your claim?
Send us the letter, the estimate or just a description of what happened. A licensed public adjuster will review it at no cost and tell you plainly what we see, including when we don’t see a path. No recovery, no fee.
Prefer to read first? Get the free digital edition of Armando’s book, The Insurance Game: And How To Win It. Schedule a free consult Public adjuster services Read chapter guides.
Armando Ferrer
Licensed Public Adjuster · American Financial Claims · Florida firm license G288962
Armando leads public adjusting work at American Financial Claims, a public adjusting firm based in Brickell, Miami. Armando Ferrer is individually licensed in 15 states; the firm entity license is Florida only (G288962). He is the author of The Insurance Game: And How To Win It. Consultations in English and Spanish. More about Armando.
Educational information only, not legal advice. Scenarios in this article are general illustrations, not real cases or clients. Coverage, deadlines and outcomes depend on your policy, your state and your facts, and no result is guaranteed. Statute references are to the Florida Statutes as published by the Florida Legislature; other states’ rules differ. American Financial Claims is a public adjusting firm, not a law firm.