The Insurance Game · Part II
Property claim mistakes people make in the first 48 hours
The early errors that shrink a claim: casual statements, thrown-away materials, the wrong contractor, and signing papers you have not read.
By Armando Ferrer, Licensed Public Adjuster
American Financial Claims · Florida firm license G288962
Published 4 min read
In this article (4 sections)
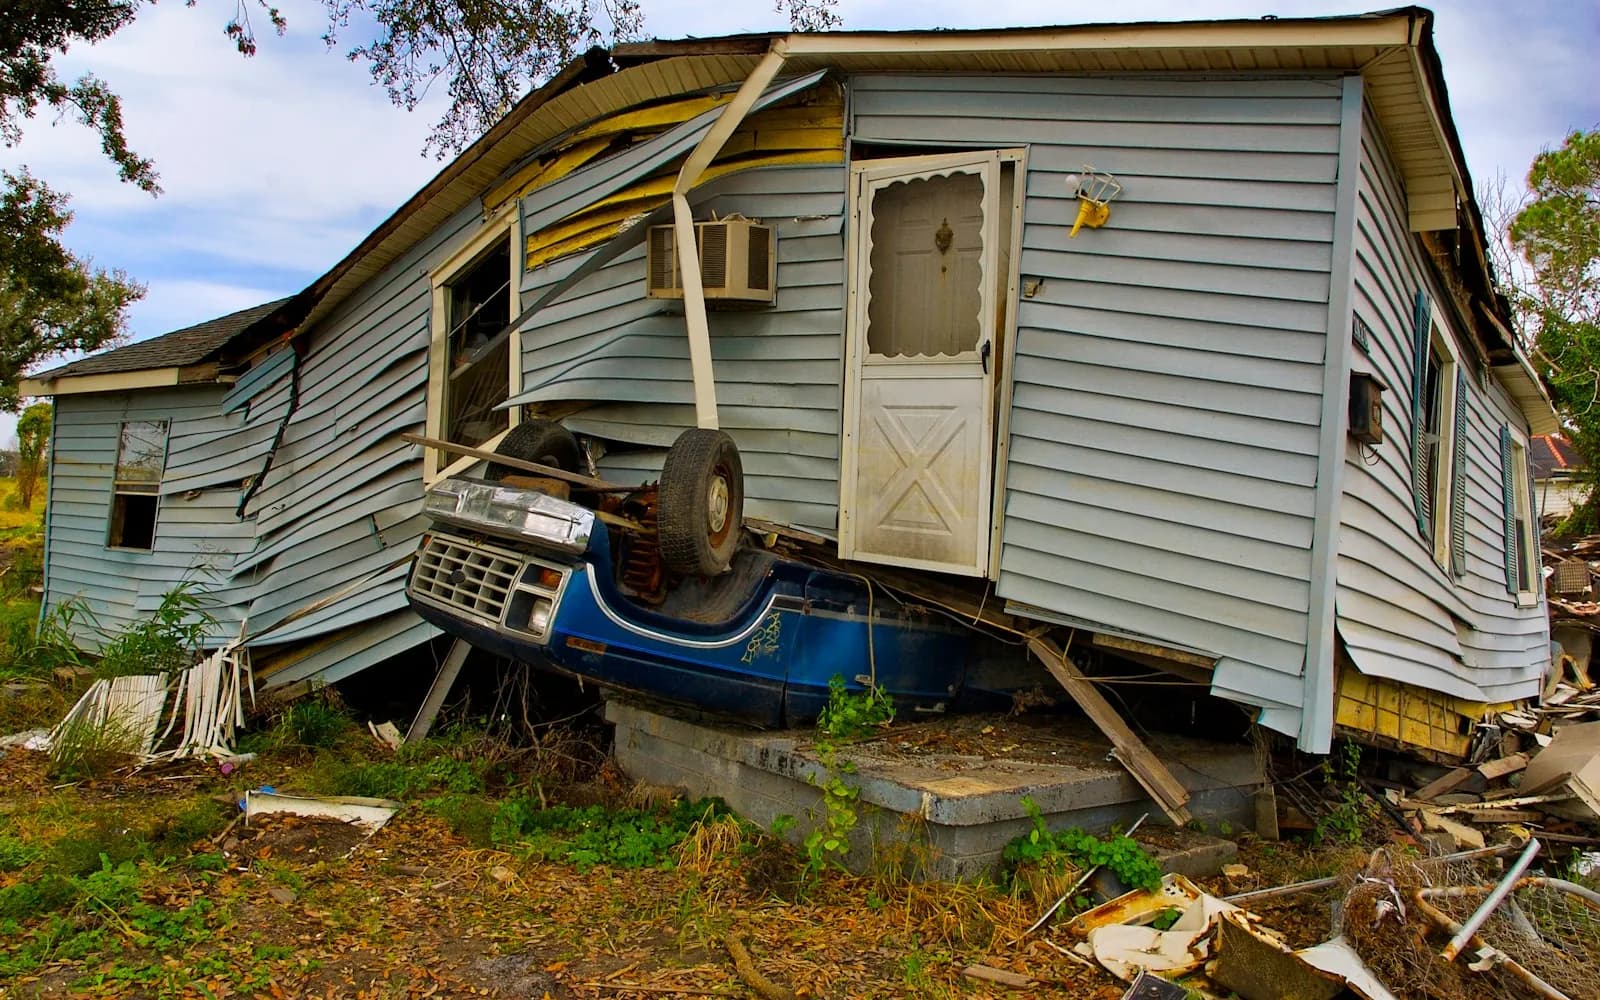
Most claim damage is not done by the storm. It is done in the two days afterward, when people are tired, displaced, and trying to be helpful on the phone.
American Financial Claims sees the same pattern across Florida and the other states where the firm is licensed: a loose sentence, a dumpster, or a one-page release that closes issues the homeowner did not know were open.
These are original notes for policyholders, not a reprint of The Insurance Game. If the loss just happened, call (239) 444-8101 and talk to a public adjuster before you talk to the insurer.
Saying more than the facts
Cause of loss, prior leaks, and “how old is the roof” are coverage questions. Answering them from memory, on a recorded line, creates a transcript you cannot edit. You can report that damage occurred, where it is, and what you did to stop it from getting worse, and leave opinions for later.
- Do not speculate that the damage is “probably wear and tear.”
- Do not estimate dollar amounts you have not measured.
- Do not agree that the inspection “looked complete” while you are still finding wet drywall.
- Ask for a copy of any recorded statement.
If a denial later quotes your own words, this is usually where they came from. The companion piece on how carriers build the file shows why that first note matters.
Throwing the evidence away
Wet carpet, swollen cabinets, and torn shingles are evidence. Once they are in a landfill, the file is left with whatever photos happened to get taken. Mitigate so the damage does not spread — dry the structure, tarp a roof — but do not start permanent demolition until the loss is documented.
Keep until the scope is agreed
- A labeled photo set before anything is moved
- Samples of flooring, shingles, or cabinetry if matching is in dispute
- Moisture readings or the mitigation company’s drying log
- Receipts for tarps, fans, and emergency board-up
Paper people sign because they want the check
A proof of loss, a release, or a contractor’s assignment can close rights you still need. Read the document for the words “full and final,” “release,” and “all claims.” If you do not understand it, do not sign it on the tailgate of a truck.
Contractor traps are a cousin of this mistake. An assignment of benefits or a contract that lets someone negotiate your claim can conflict with hiring a public adjuster later. Ask who is being paid, from which check, and whether you can still choose your own repair scope.
Pause the signature
American Financial Claims will look at a form with you on a free consult. Call (239) 444-8101 or book a time before you sign.
Deadlines still run while you wait
Being careful is not the same as going silent. In Florida, section 627.70132 of the Florida Statutes generally requires notice of a property claim within one year of the date of loss, and notice of a supplemental claim within 18 months. Other states and some policies are stricter. Missing notice is not a documentation style issue. It can end the claim.
The practical split: document before you narrate, and report before the window closes. How to document the loss is the next step. The longer playbook is the free digital edition on the book download form.
Frequently asked questions
Can I start drying the house before the adjuster arrives?
Yes. Stop additional damage. Photograph first, keep receipts, and hold permanent tear-out until the damaged materials are documented.
What if I already gave a recorded statement?
Write down what you remember saying and ask the carrier for a copy. A public adjuster can still help organize what remains. Call American Financial Claims at (239) 444-8101.
Is this the same text as the book?
No. These pages are original articles inspired by the book’s themes. Download the free edition from the existing book form.
Free digital edition
Get the book, then decide your next move.
American Financial Claims will email the free digital edition of The Insurance Game: And How To Win It. Same download form as the book page. If a claim is open, talk to a public adjuster before you talk to the insurer.
Prefer a set time? Schedule a free consult · Public adjuster services · All chapter guides
Armando Ferrer
Licensed Public Adjuster · American Financial Claims · Florida firm license G288962
Armando leads public adjusting work at American Financial Claims, a public adjusting firm based in Brickell, Miami and licensed in 15 states. He is the author of The Insurance Game: And How To Win It. Consultations in English and Spanish. More about Armando.
Educational information only, not legal advice. Scenarios in this article are general illustrations, not real cases or clients. Coverage, deadlines and outcomes depend on your policy, your state and your facts, and no result is guaranteed. Statute references are to the Florida Statutes as published by the Florida Legislature; other states’ rules differ. American Financial Claims is a public adjusting firm, not a law firm.