The Insurance Game · Estimates
Carrier estimate tactics that leave a property claim underpaid
Missing rooms, cheap material grades, depreciated totals, and delays that wear you into accepting the first number.
By Armando Ferrer, Licensed Public Adjuster
American Financial Claims · Florida firm license G288962
Published 4 min read
In this article (4 sections)
An insurance estimate can be mathematically tidy and still be wrong. The software did what it was told. The question is whether anyone told it about the rooms, the code items, and the materials that were actually on your building.
American Financial Claims compares carrier estimates to the building, not to a feeling that the check “seems low.” This article explains the patterns. It does not reprint The Insurance Game. Download that edition free if you want the author’s full walkthrough, and read how to review an estimate for a line-by-line companion.
If a check is already in your hand and it will not fund the repair, call (239) 444-8101 before you treat it as the end of the claim.
Scope errors hide inside a neat price
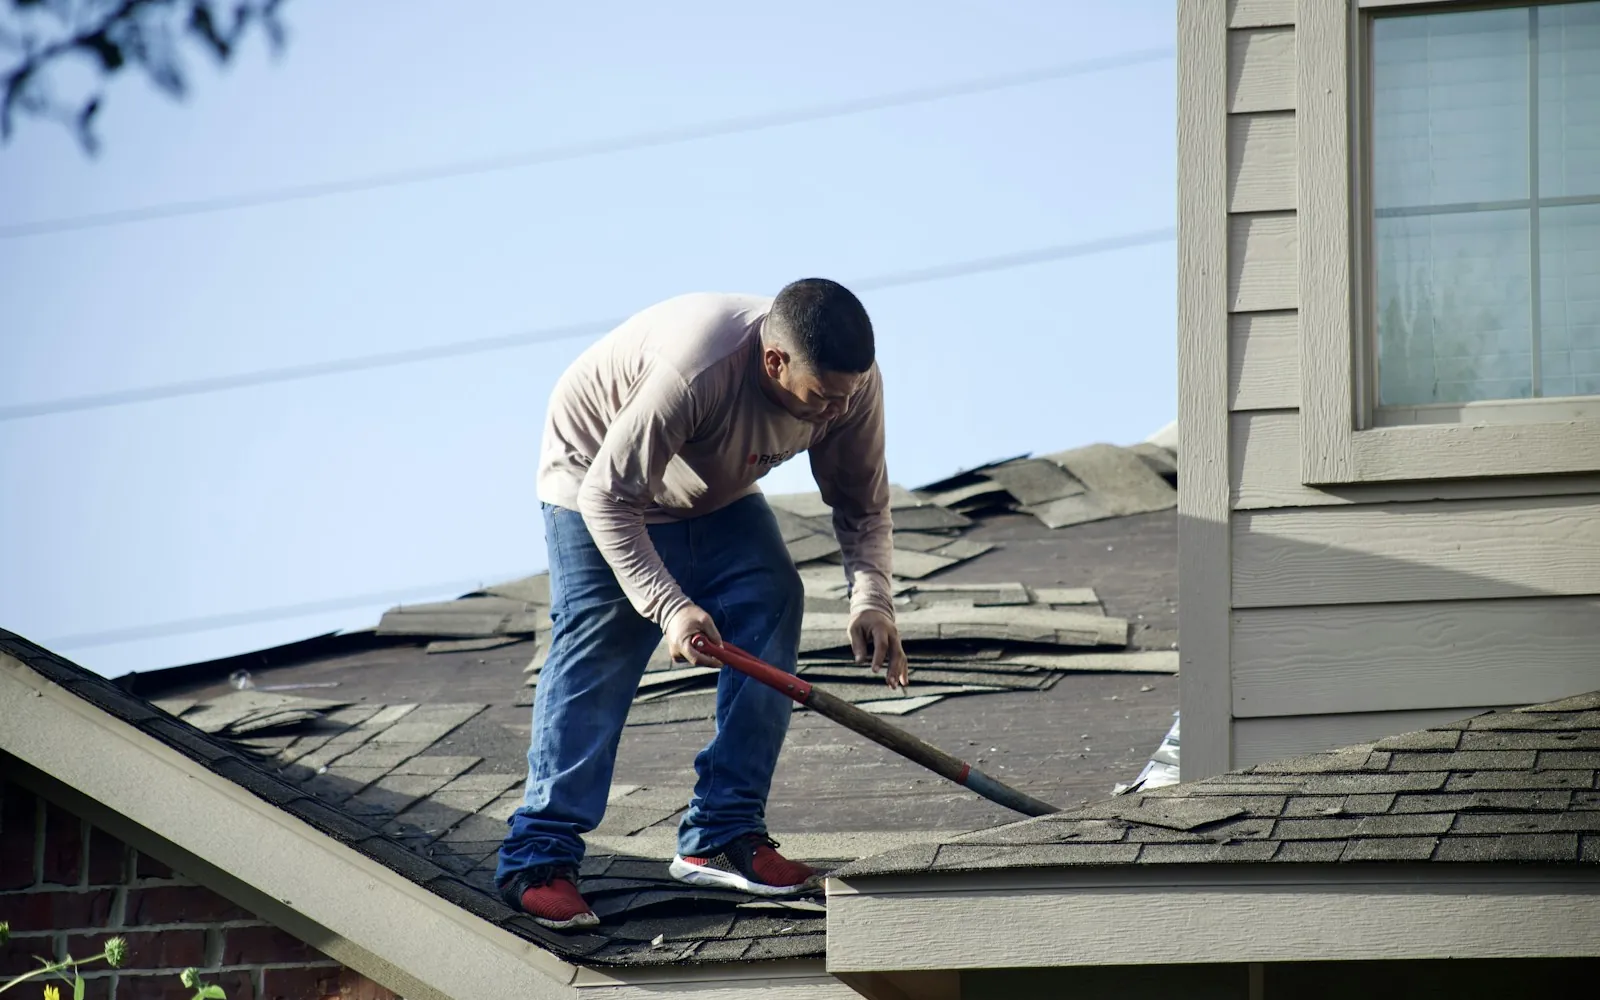
Unit prices get the argument. Missing scope does the damage. A per-square price for shingles does not matter if the decking, drip edge, and flashing were left off. A drywall price does not matter if the estimate stops at the paint line and ignores the wet insulation behind it.
- Rooms or elevations that were never inspected
- Like-kind materials swapped for a builder-grade default
- Detach-and-reset labor omitted where finishes have to come off to dry the wall
- Code, matching, or ordinance items marked as “not covered” without the endorsement checked
- Overhead and profit removed on a job that needs more than one trade
Put the carrier estimate next to a contractor scope and mark only the differences. Our estimate comparison notes and the underpaid-claim guide show the same comparison in more detail.
Depreciation, deductibles, and the check that is not the estimate
The estimate total, the deductible, and the recoverable depreciation are three different numbers. On a replacement-cost policy, depreciation is often held back until repairs are done and documented. People deposit the actual-cash-value check and think the claim is over, then discover the held-back amount had a deadline.
Read the payment letter
Look for “recoverable depreciation,” “holdback,” and the date you must finish repairs or request the balance. That date is not always the same as the claim-notice deadline.
A deductible is owed by you. It should be taken once, not quietly duplicated across coverages. If two checks each subtract the full deductible, ask for the worksheet before you argue about shingles.
Delay is a tactic even when nobody admits it
Not every slow file is a strategy. Some are short-staffed desks. The effect on you is the same: you get tired, the contractor moves to another job, and the first number starts to look like relief. Common stalls include “waiting on an engineer,” unanswered supplement emails, and inspections that keep getting reset.
- Keep every request in writing and note the date.
- Ask what document, exactly, is missing.
- Send the missing item once, completely, instead of in fragments.
- If weeks pass with no decision, ask for the supervisor and the coverage position in writing.
Silence is not consent, but it also does not pause every deadline. Track notice and supplement dates while you wait. Delayed claims explains how American Financial Claims treats a stalled file.
What to do with the first number
Before you accept the estimate
- Match every room you photographed to a section of the estimate
- Circle materials that are not what is on the house
- Separate the deductible from depreciation holdback
- List items your contractor says are required and missing
- Do not sign a release just to get the undisputed portion, unless the letter says the rest stays open
You can often be paid for undisputed items while the rest is supplemented. Get that in writing. If the gap is large, a public adjuster can price and present the difference. Schedule a review or call (239) 444-8101. The free book download remains on this form.
Frequently asked questions
If I cash the check, did I accept the estimate?
Not always. Read the letter. Some payments are partial and say so. Some releases are full and final. When the wording is unclear, do not guess. Call American Financial Claims before you sign anything extra.
Can I use my own contractor’s estimate?
Yes. A real scope from someone who will do the work is useful evidence. It still has to be tied to the policy and to what was damaged, not to a wish list of upgrades.
Are you selling a new way to buy the book?
No. The free digital edition uses the download form already on /book. These articles only link to it.
Free digital edition
Get the book, then decide your next move.
American Financial Claims will email the free digital edition of The Insurance Game: And How To Win It. Same download form as the book page. If a claim is open, talk to a public adjuster before you talk to the insurer.
Prefer a set time? Schedule a free consult · Public adjuster services · All chapter guides
Armando Ferrer
Licensed Public Adjuster · American Financial Claims · Florida firm license G288962
Armando leads public adjusting work at American Financial Claims, a public adjusting firm based in Brickell, Miami and licensed in 15 states. He is the author of The Insurance Game: And How To Win It. Consultations in English and Spanish. More about Armando.
Educational information only, not legal advice. Scenarios in this article are general illustrations, not real cases or clients. Coverage, deadlines and outcomes depend on your policy, your state and your facts, and no result is guaranteed. Statute references are to the Florida Statutes as published by the Florida Legislature; other states’ rules differ. American Financial Claims is a public adjusting firm, not a law firm.