Hurricane Isaias Claim Guide
Florida Statutes That Protect You, and How a Public Adjuster Can Help With Your Isaias Claim
Florida regulates public adjusters closely, and many of those rules exist to protect homeowners. Here is what a public adjuster does, the legal protections you have when you hire one, and how American Financial Claims works on a Hurricane Isaias claim.
By American Financial Claims
Hurricane Updates & Insurance Claim Resources · Florida firm license G288962
Published 9 min read
In this article (8 sections)
After a hurricane, homeowners hear from a lot of people: insurance adjusters, contractors, roofers, and sometimes public adjusters knocking on the door. It is fair to wonder who is on your side, and what rules they have to follow.
This article explains what a licensed public adjuster does, walks through the Florida statutes that protect you when you hire one, and describes how American Financial Claims handles a Hurricane Isaias claim. It is general information, not legal advice, and it is not a promise of any result. Every claim depends on the policy and the facts.
What a public adjuster does
Florida law defines a public adjuster in Fla. Stat. 626.854 as someone who, for pay, prepares, completes or files an insurance claim for an insured, or helps negotiate the settlement of a claim covered by an insurance contract. In plain terms: the insurance company has its adjuster, and a public adjuster is the licensed professional who works for you.
- Inspects and documents the damage, inside and out
- Reviews your policy, endorsements and deductibles
- Writes a detailed, itemized estimate of the repair
- Presents the claim to the insurer and handles the back-and-forth
- Negotiates with the insurer’s adjuster toward a settlement
What a public adjuster does not do: give legal advice, or handle claims for bodily injury. The statute says so directly. A public adjuster also does not work for the insurance company and does not sell insurance.
Before you hire anyone, check the license. You can look up any Florida adjuster by name or license number on the Department of Financial Services Licensee Search. American Financial Claims is a licensed Florida public adjusting firm, license G288962, and Armando Ferrer is individually licensed as a public adjuster in 15 states.
Fee protections for Isaias claims
Florida caps what a public adjuster can charge. Under 626.854(11), for claims based on events that are the subject of a Governor’s state of emergency, the fee may not exceed 10% of the claim payments for claims made during the year after the declaration. Outside an emergency, the cap is 20%. Governor DeSantis declared a state of emergency for Isaias in Executive Order 26-202 on October 6, 2026, later amended to add counties.
- No fee on money already paid. A public adjuster generally gets 0% of payments the insurer made, or agreed in writing to make, before the contract was signed.
- Small fee when limits are paid fast. If the insurer pays or commits in writing to pay the full policy limit on a coverage within 14 days after the loss, or within 10 days after the contract, whichever is later, the cap on that coverage is 1%.
- Reopened and supplemental claims. The fee can only be based on new money obtained after the contract, never on earlier payments, and still cannot exceed the caps above.
- Not on your deductible. Claim payments do not include the deductible, and the fee cannot be based on it.
- Living expenses need a separate agreement. A fee on additional living expense payments requires a separate signed disclosure.
- No raise for litigation. The fee rate cannot go up just because the claim ends up in court.
Residential and condo policies
Most of these protections, including the fee caps, cancellation rights and solicitation rules, are in subsections (5) through (18) of 626.854, which the statute says apply only to residential property policies and condominium unit owner policies. Commercial claims follow different rules, so ask about the contract terms for a business property.
Your right to cancel
You are never locked in the moment you sign. Under 626.854(7), you can cancel a public adjuster contract for any reason, without penalty, within 10 days after signing. When the contract is based on events covered by a Governor’s state of emergency, like Isaias, the window is the longer of 30 days after the date of loss or 10 days after signing.
The contract has to spell out that right in large bold type right above your signature, and cancellation notice is sent in writing by certified mail or another method with proof of mailing, to the address in the contract. You can also cancel without penalty if the public adjuster does not provide you and your insurer a written estimate within 60 days of the contract, unless the delay is beyond the adjuster’s control.
Rules on how public adjusters do business
- A written contract first. A public adjuster cannot collect a fee on payments to you without a written contract.
- An itemized estimate within 60 days. The written estimate must be itemized per unit, covering materials, labor, equipment and supplies, and kept for at least 5 years.
- Limited solicitation hours. A public adjuster may solicit only Monday through Saturday, between 8 a.m. and 8 p.m.
- No inducements. No loans or advances to clients, no gifts worth more than $25 to win a contract, and no gift cards, cash or deductible waivers in exchange for a roof inspection or roof claim.
- No ads that mislead. Florida bans public adjuster advertising that invites a claim without covered damage, offers money to file, claims there is “no risk,” or looks like it comes from the government.
- Answers within 14 days. A public adjuster must respond with specific information to a written or electronic request for the status of your claim within 14 days.
Florida law also protects your representation in dealings with the insurer: for residential and condo claims, the insurer cannot exclude your public adjuster from its in-person meetings with you, and it must work with the public adjuster to try to agree on the scope of the loss. Our article on your rights under Florida law after Isaias covers those rules and the insurer’s deadlines.
Matching and code upgrades under 626.9744
Fla. Stat. 626.9744 sets two rules for homeowners policies that settle on repair or replacement cost, unless the policy says otherwise:
- Matching. When replaced items do not match in quality, color or size, the insurer must make reasonable repairs or replacement of items in adjoining areas. The insurer can consider cost, how much uniformity can be achieved, the remaining useful life of undamaged parts and other factors.
- Collateral damage and code. Covered physical damage caused while making a repair is included in the loss, and you generally cannot be required to pay for betterment required by ordinance or code beyond your deductible, unless the policy specifically excludes or limits it.
These rules are a frequent source of disagreement after storms like Isaias, where a roof section, a run of tile or a wall of cabinets is damaged and the rest is not. Documenting the whole area, not just the damaged piece, helps. See why Isaias claims get underpaid or denied for more.
How American Financial Claims works on an Isaias claim
- Free claim review. We look at your damage, your policy and where the claim stands, at no cost and with no obligation. Start online with a free claim review or call (239) 444-8101.
- Inspection and documentation. We inspect the property and document roof, wind, water and contents damage with photos, measurements and notes tied to the cause of loss. Call (727) 342-1077 to schedule an inspection.
- Policy review. We review coverages, exclusions, the hurricane deductible and how wind and flood apply. See the hurricane deductible explained.
- Detailed estimate. We write an itemized, line-by-line estimate of the full repair scope, as Florida law requires within 60 days of the contract.
- Presenting the claim. We submit the estimate and documentation to your insurer and keep the file organized.
- Negotiation. We handle the back-and-forth with the insurer’s adjuster through settlement, and explain options like state mediation or policy appraisal if there is a dispute.
Most property claims settle without a lawsuit. A lawyer is the right call when you need legal advice or the dispute is headed to court, and we will tell you plainly if your claim is reaching that point.
If you hire us, our fee is a percentage of the recovery, disclosed in a written contract before you sign, within the limits above. No recovery, no fee. Results depend on your policy and the facts and are not guaranteed.
What the research says
In one hurricane-claim category, a 2010 report by Florida’s Office of Program Policy Analysis and Government Accountability (OPPAGA Report 10-06) found median payments of $17,187 for claims with public adjuster representation versus $2,029 without, about 747% higher. That study covered Citizens claims filed in 2008 and 2009 relating to 2005 hurricanes. It is historical research, the figures are before public adjuster fees, and it is not a prediction of results for any claim, including yours.
Next steps after Isaias
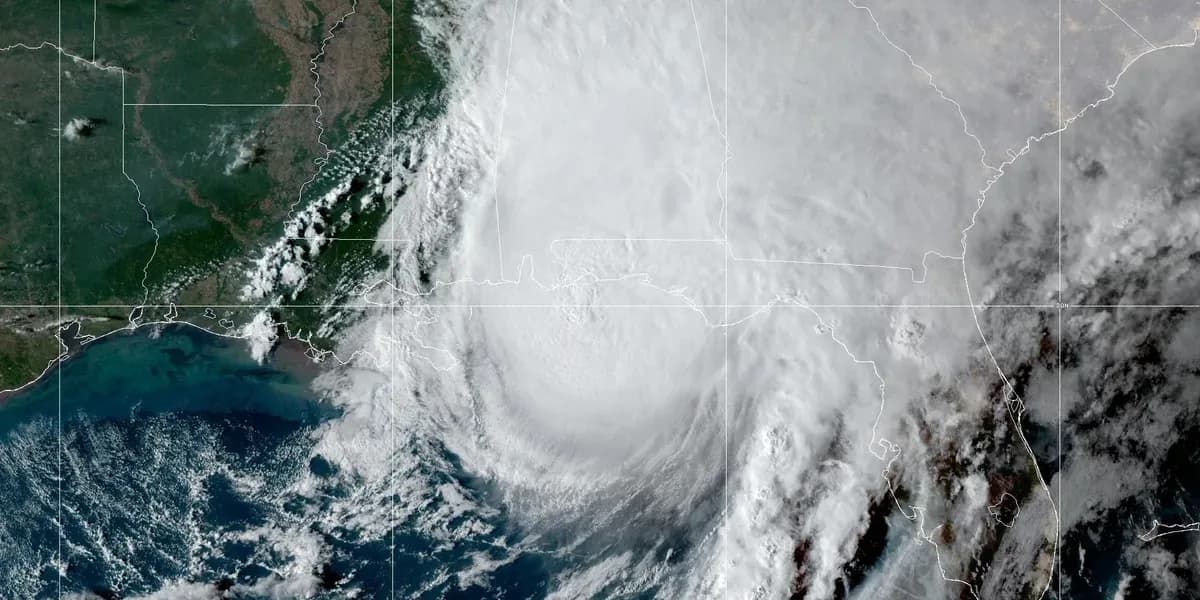
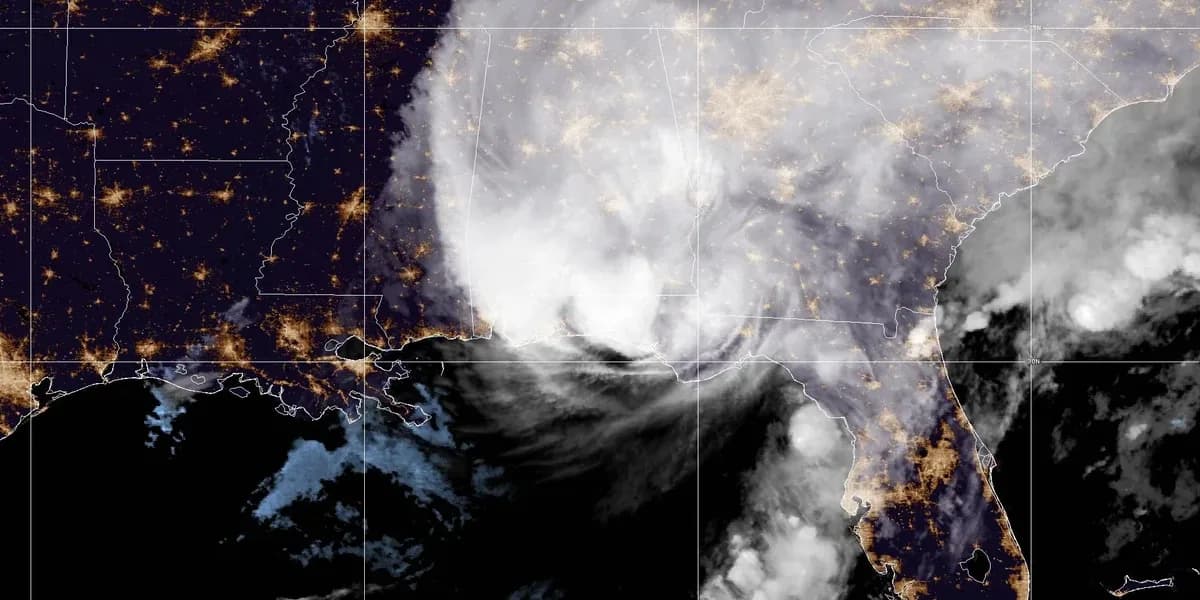
Isaias made landfall near Destin on October 9, 2026 as a 105 mph Category 2 hurricane. Under Florida law, notice of a new Isaias claim is generally due within 1 year of that date, and a supplemental claim within 18 months, but sooner is always better. Our step-by-step filing guide and first Isaias guide cover the basics, and our storm page has the full timeline. Local guides: Pensacola, Destin and Fort Walton Beach, Panama City.
Frequently asked questions
How much can a public adjuster charge on a Hurricane Isaias claim?
For residential and condo claims tied to a Governor’s state of emergency, Fla. Stat. 626.854 caps the fee at 10% of claim payments for claims made during the year after the declaration. Lower limits apply in some situations, such as 0% on payments made before the contract and 1% when policy limits are paid within the statute’s short window.
Can I cancel a public adjuster contract after Isaias?
Yes. For contracts based on events covered by a Governor’s state of emergency, you can cancel without penalty within 30 days after the date of loss or 10 days after signing, whichever is longer. You can also cancel if the public adjuster does not provide a written estimate within 60 days, unless the delay is beyond their control.
Is a public adjuster the same as a lawyer?
No. A public adjuster documents, estimates and negotiates your property claim but cannot give legal advice. Most property claims settle without a lawsuit; a lawyer is the right call when you need legal advice or the dispute is headed to court.
How do I check that a public adjuster is licensed in Florida?
Use the Florida Department of Financial Services Licensee Search at licenseesearch.fldfs.com and search by the adjuster’s name or license number. American Financial Claims’ Florida firm license is G288962.
Educational information only, not legal advice. Scenarios in this article are general illustrations, not real cases or clients. Coverage, deadlines and outcomes depend on your policy, your state and your facts, and no result is guaranteed. Statute references are to the Florida Statutes as published by the Florida Legislature; other states’ rules differ. American Financial Claims is a public adjusting firm, not a law firm.