Hurricane Updates & Insurance Claim Resources
Hurricane Isaias 2026: The Storm Is Coming. Is Your Insurance Company Ready to Pay?
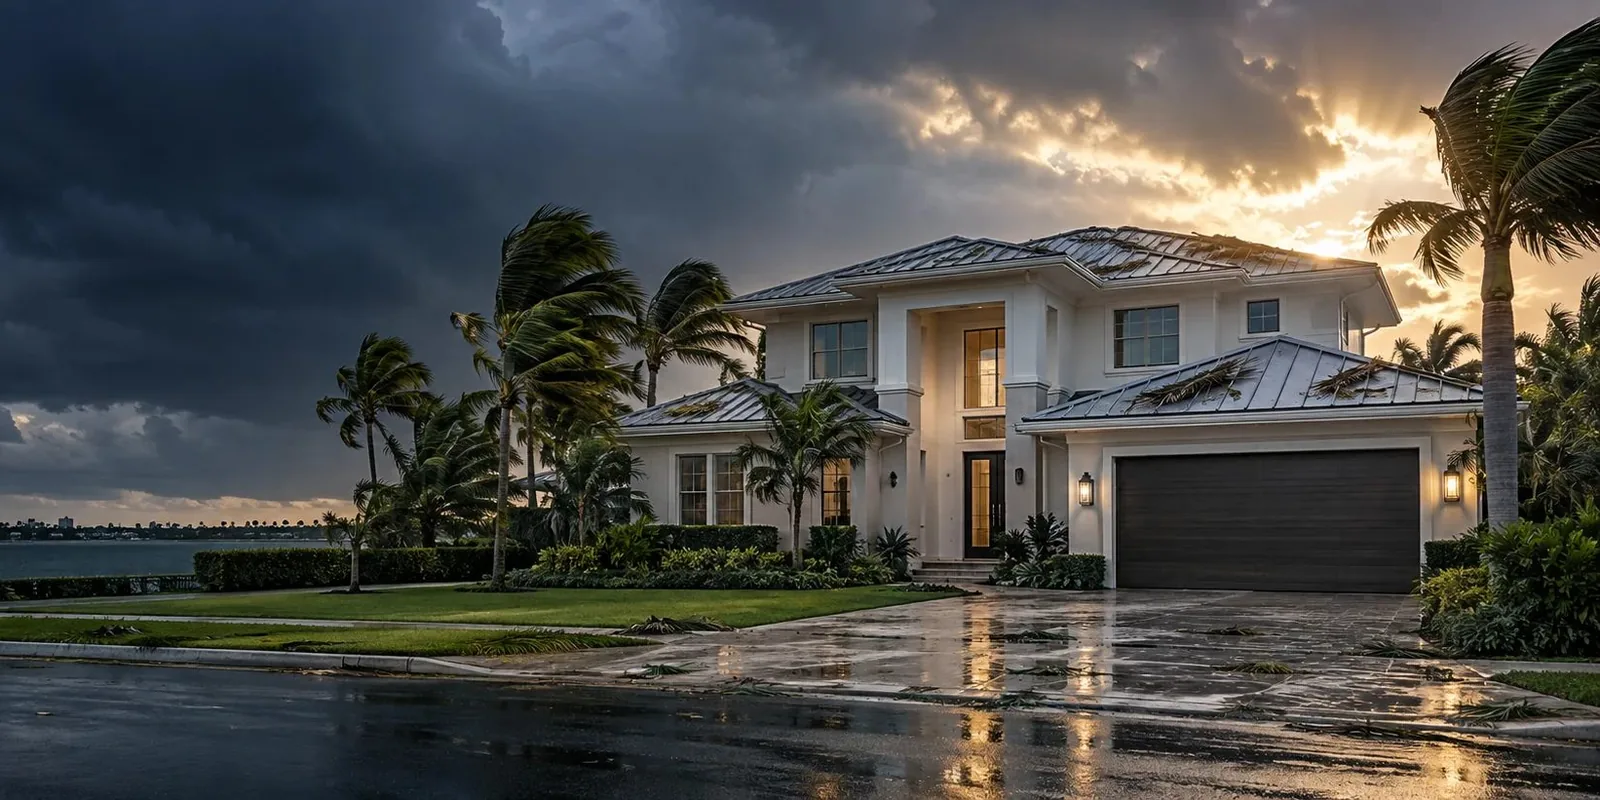
Hurricane Isaias is strengthening in the Gulf of Mexico, putting Pensacola, the Florida Panhandle, and surrounding Gulf Coast communities on high alert. Here’s what every homeowner needs to know before and after the storm.
By American Financial Claims
Hurricane Updates & Insurance Claim Resources · Florida firm license G288962
Published 7 min read
In this article (9 sections)
The Gulf Coast Is Running Out of Time to Prepare
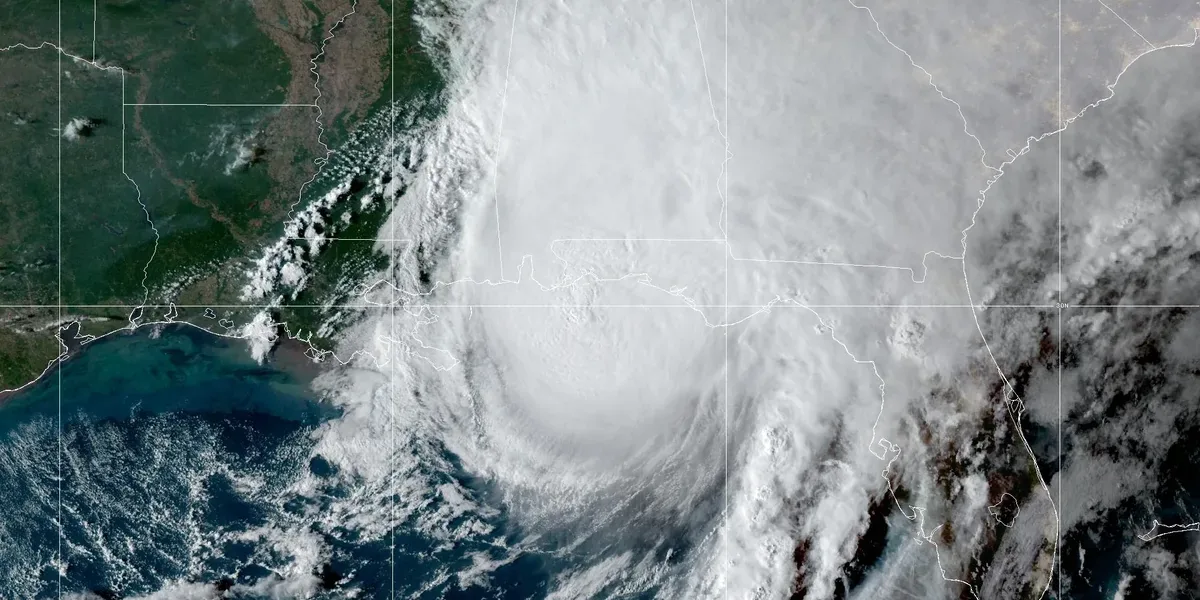
Hurricane Isaias has officially reached Category 1 strength, and communities along the northern Gulf Coast are preparing for potentially dangerous conditions.
According to the National Hurricane Center’s late October 7 advisory, Isaias had maximum sustained winds of 75 mph as it moved east-northeast through the Gulf of Mexico.
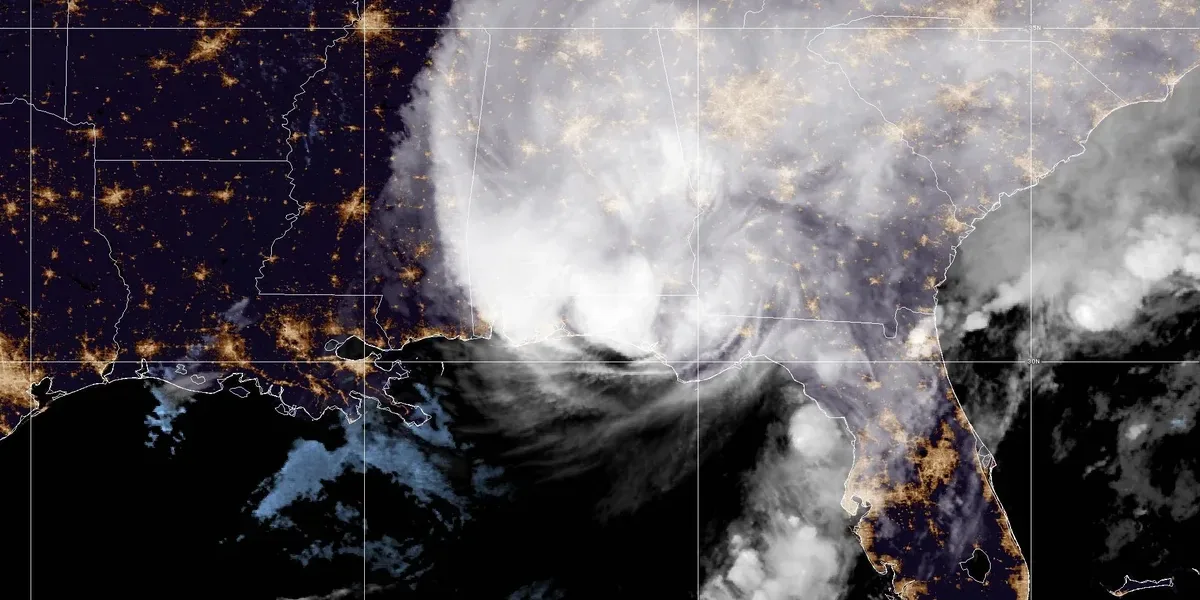
The National Hurricane Center’s final advisory on Isaias, issued at 5 a.m. ET October 10, said the storm, which made landfall near Destin, Florida, Friday evening at 105 mph, had weakened to a post-tropical cyclone with maximum sustained winds of 35 mph about 25 miles south-southwest of Montgomery, Alabama, moving north at 14 mph, and is forecast to dissipate Sunday. All Storm Surge and Tropical Storm Warnings were discontinued, with no watches or warnings in effect, though NHC still expects 4 to 8 inches of rain (locally up to 15) across the Florida Panhandle and Big Bend, with considerable flooding impacts likely.
The storm could bring destructive winds, coastal flooding, heavy rainfall, and tornadoes to parts of Florida, Alabama, and Mississippi.
For homeowners in Pensacola, Pensacola Beach, Gulf Breeze, Navarre, Fort Walton Beach, Destin, and surrounding communities, now is the time to prepare.
But there’s something many homeowners don’t think about until it’s too late.
Surviving the hurricane is only half the battle. The other half is dealing with your insurance claim.
And that battle can sometimes last months.
Your Insurance Company Has Adjusters. Who’s Looking Out for You?
When a hurricane damages your home, your insurance company will typically send an adjuster to inspect the property.
That adjuster is working on behalf of the insurance company.
But who is representing you?
That’s where a licensed public adjuster comes in.
At American Financial Claims, we work for policyholders, not insurance companies.
Our job is to help homeowners understand their coverage, document their losses, prepare their claims, and pursue the insurance benefits they’re entitled to under their policies.
Think of it this way:
The insurance company has its team. You deserve someone in your corner, too.
7 Things Every Homeowner Should Do Before Hurricane Isaias Arrives
- Photograph your property today. Take clear pictures and videos of your roof, ceilings, walls, windows, doors, flooring, furniture, and valuable belongings.
- Find your insurance policy. Review your hurricane deductible, coverage limits, endorsements, and exclusions.
- Protect important documents. Store insurance policies, identification, mortgage documents, and photographs somewhere secure and accessible.
- Prepare for power outages. Charge devices, secure emergency supplies, and follow local emergency management instructions.
- Protect your home when safe. Secure outdoor items, close protective shutters if available, and take reasonable precautions without exposing yourself to danger.
- Know the difference between wind and flood coverage. Do not assume all hurricane-related damage will be covered under one policy.
- Put safety first. Follow evacuation orders and never remain in an unsafe structure to protect property.
Your family’s safety is always more important than your insurance claim.
The First 48 Hours After Isaias: What You Do Matters
Once authorities confirm that it is safe to return, take steps to document your loss and protect your property.
- Photograph visible damage before cleanup whenever safely possible.
- Report your loss promptly according to your policy’s requirements.
- Take reasonable steps to prevent additional damage.
- Save invoices, emergency repair receipts, and mitigation records.
- Avoid discarding damaged materials before documenting them, unless safety or health conditions require removal.
- Keep written records of conversations with the insurance company.
- Consider having a licensed public adjuster evaluate your damage and review the claim.
Do not put off emergency repairs or necessary water mitigation while waiting for an insurance inspection.
Just make sure you document what happened and maintain records of the work performed.
Five Insurance Claim Mistakes That Could Cost You Thousands
Mistake #1: Assuming the First Estimate Includes Everything
An insurance company estimate may not account for every damaged component, necessary repair, or applicable cost.
A detailed, properly supported estimate can help identify differences.
Mistake #2: Overlooking Damage You Cannot See
Moisture intrusion, damaged insulation, roof components, and other concealed conditions may require additional investigation.
Mistake #3: Failing to Document Your Loss
Photos, videos, receipts, repair estimates, and moisture readings can make a meaningful difference when documenting the cause and extent of damage.
Mistake #4: Not Understanding Your Hurricane Deductible
Florida hurricane deductibles can be significantly different from ordinary policy deductibles.
Understanding how yours applies is important before making financial decisions about repairs.
Mistake #5: Believing You Have to Handle Everything Yourself
You have the option to obtain professional representation and assistance with your property insurance claim.
A licensed public adjuster can help you navigate the claim process, understand the insurance company’s estimate, and present properly documented damages.
Pensacola, We’re Here to Help You Recover
Hurricanes don’t care whether your roof is new.
They don’t care whether you just remodeled your kitchen.
And they certainly don’t care whether you have the savings to repair your home.
At American Financial Claims, we understand how overwhelming property damage can be.
We help property owners navigate insurance claims involving:
- Hurricane and wind damage
- Roof damage
- Water intrusion
- Interior property damage
- Commercial property losses
- Underpaid or disputed insurance claims
- Supplemental damage assessments
We don’t represent insurance companies. We represent policyholders.
Our goal is to make sure your loss is properly documented and your claim receives the attention it deserves.
Hurricane Isaias Is a Reminder: Know Your Rights Before You Need Them
A hurricane can change your life in a matter of hours.
Your home, belongings, business, and financial stability may all be affected.
But when the storm passes, you don’t have to navigate the insurance claim process without professional guidance.
Understanding your policy and properly documenting your damage are among the most important steps you can take.
The storm may be beyond your control. How you prepare for the claim doesn’t have to be.
Hurricane Damage? Get a FREE Property Inspection.
Your insurance company has professionals protecting its interests. Make sure yours are represented, too.
American Financial Claims offers free property inspections and insurance claim evaluations.
Whether your property suffers roof damage, water intrusion, or major structural damage, our team can help you evaluate the situation and understand your options.
For official storm forecasts, watches, warnings, and evacuation information, follow the National Hurricane Center and your local emergency management officials.
Educational information only, not legal advice. Scenarios in this article are general illustrations, not real cases or clients. Coverage, deadlines and outcomes depend on your policy, your state and your facts, and no result is guaranteed. Statute references are to the Florida Statutes as published by the Florida Legislature; other states’ rules differ. American Financial Claims is a public adjusting firm, not a law firm.